
The workload
Getting a usable multiple out of Flippa's own published data means reading past the headline ranges to the table documenting actual closed sales. Verified: Flippa's own SaaS valuation multiples page, published 31 January 2025 and last updated by the marketplace in February 2026, includes a table titled "Notable Recent SaaS Sales on Flippa" listing individual transactions by MRR, revenue multiple, profit multiple, profit margin, and sale price. The workload for a founder using this page correctly is matching their own business's category, margin, and MRR band to the closest documented comparable, rather than applying one headline number to a different kind of business.
What the documents show
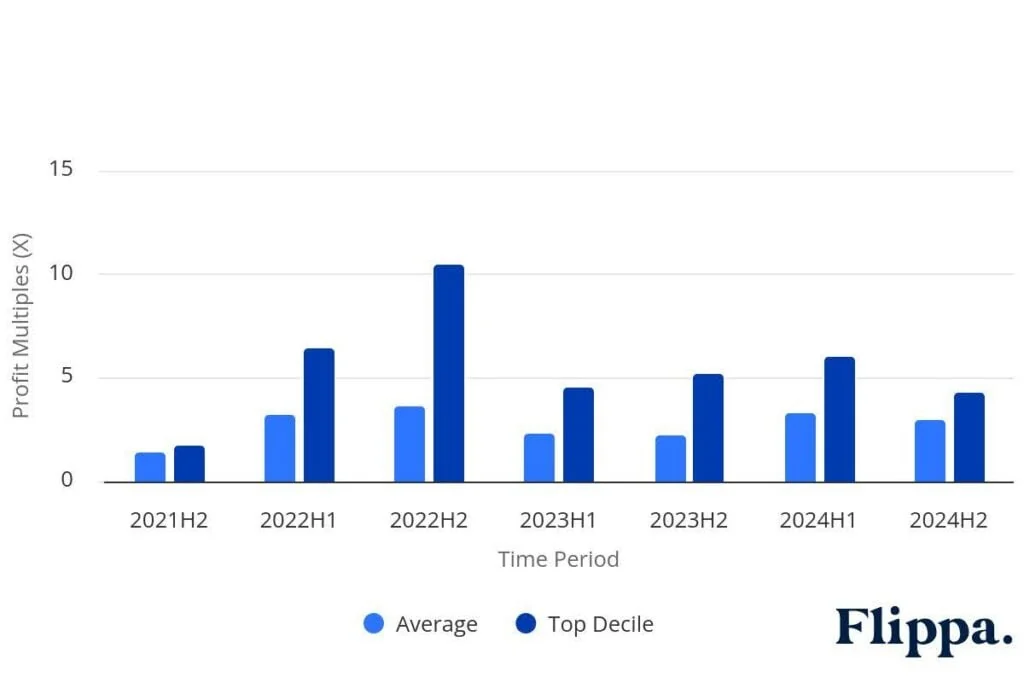
Verified: Flippa's page states that "by the end of 2024, Flippa facilitated the sale of 795 SaaS businesses," and breaks out profit and revenue multiples by industry "over the past 18 months" — for example, Marketing Tools & Automation at 5.9x profit and 2.1x revenue, Education at 4.1x profit and 3.2x revenue, Health & Wellbeing at 3.9x profit and 1.8x revenue, Internet & Security at 3.4x profit and 1.9x revenue, and CRM Tools at 2.6x profit and 2.1x revenue. Those industry figures are Flippa's own transaction data, framed as how "different categories performed on Flippa." Separately, the page states broader ranges, "3x to 5x ARR" for private SaaS companies under 20 percent growth up to "7x to 10x ARR" for high-growth companies, and "7x to 8x ARR" median for public SaaS companies, without citing a source for those broader figures, so they read as general market commentary rather than Flippa's own sale data. This entry keeps that distinction, and does not blend Flippa's per-industry figures with Acquire.com's separately published multiples, since the two marketplaces report different samples over different periods.
The operating cost
Flippa does not charge sellers to list; its marketplace page states the platform connects sellers with "400,000+ Weekly Active Buyers" and offers paid broker services on top. The cost that matters here is the multiple gap itself: a business in CRM tools sold, per Flippa's own 18-month data, at roughly 2.6x profit or 2.1x revenue, while one in marketing automation sold around 5.9x profit at the same 2.1x revenue multiple, more than double on the profit side alone, both from the same marketplace and period.
The stop condition
Editorial: the source names no stop condition. The reasonable reading is a seller should stop anchoring to a headline multiple once they can find their own industry row in Flippa's table, since the spread between categories is wide enough that a generic figure misprices the business either way.
- Which specific industry row in Flippa's own 18-month table matches this business, not just "SaaS" broadly?
- Is the multiple being quoted Flippa's own facilitated-sale data or the page's unsourced broader market commentary?
- How does this comparable set differ from Acquire.com's own, separately reported multiples for a similar business?
Marketplace-published multiples are a starting anchor, not a valuation. Flippa's own numbers vary by more than double by category, and its broader growth-tier ranges carry no stated source, both facts worth carrying into any conversation about what a specific business is actually worth.
Sources & reading trail
States the number of SaaS businesses Flippa has facilitated selling, per-industry profit and revenue multiples over the trailing 18 months, and broader ARR-multiple ranges.
Source published: 31 January 2025 · Retrieved: 16 September 2026
States current buyer-pool size and that listing itself carries no seller fee on the base marketplace.
Source published: Not established · Retrieved: 16 September 2026
Vendor documentation, regulator records and founder-published documents establish the entry; the workload reading and the stop condition are Solo Product Office editorial analysis. This retrospective draft does not imply the site published on the event date.